

CFTC Chairman Michael Selig says increasingly autonomous AI agents could force financial regulators to rethink rules built around identifiable human traders and intermediaries. In official remarks at the CFTC’s inaugural Frontier Forum on Super Intelligence, Selig asked whether developers of trading agents could face registration obligations, who would bear liability when an agent acts unexpectedly and whether regulators may eventually need a “know-your-agent” framework. The October 28 comments were exploratory rather than an announcement of new CFTC rules.
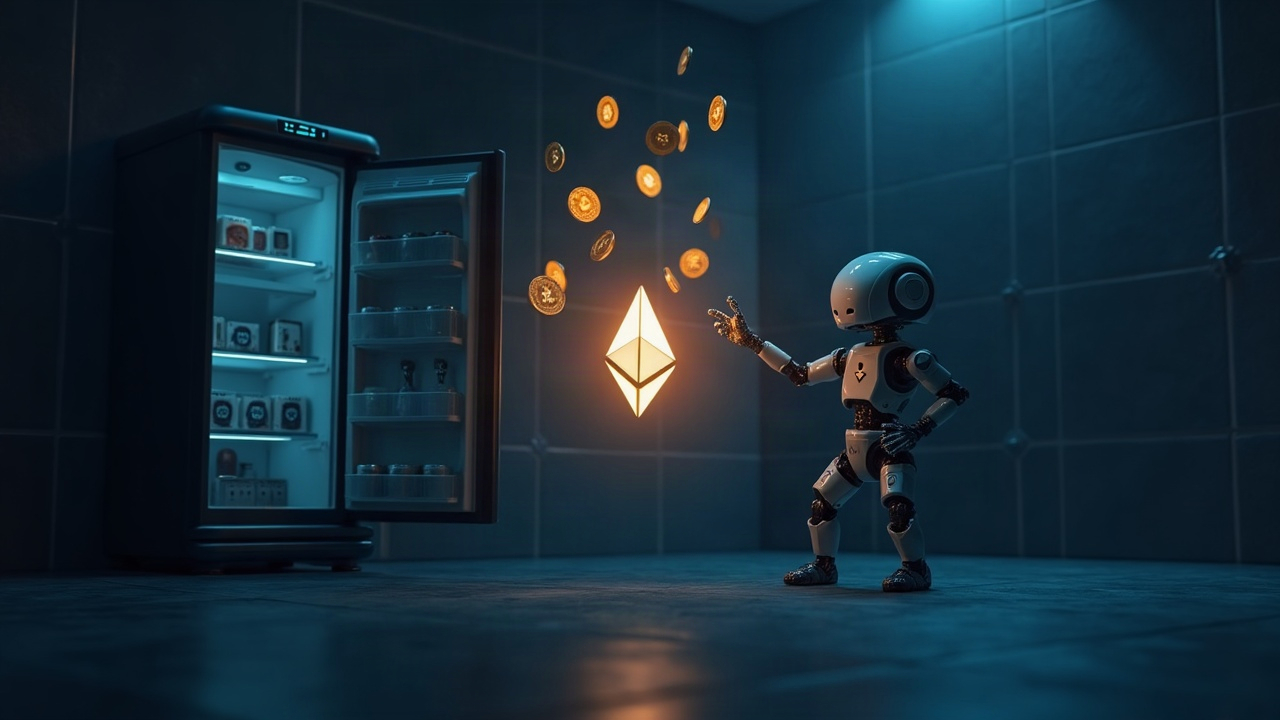
Selig illustrated the issue with an intentionally extreme example: software embedded in a refrigerator could theoretically purchase groceries using proceeds generated from staking Ether or launching a memecoin. His broader point was that blockchains already provide infrastructure through which autonomous software can custody and trade crypto assets without depending on conventional financial intermediaries. That changes the regulatory problem from simply identifying a customer to understanding which software is acting, on whose authority and with what degree of control.
Autonomous Agents Challenge Existing Accountability Models
The CFTC’s existing framework generally regulates identifiable entities according to the financial functions they perform. Autonomous software complicates that model when an agent independently identifies an opportunity and executes a transaction for a user. Selig said regulation should remain grounded in the function performed, the control exercised and the economic reality of the transaction rather than automatically treating every software developer as a financial intermediary.
That distinction is already visible in crypto infrastructure. Nunchuk’s Bitcoin tools give AI agents bounded transaction authority through multisignature controls rather than unrestricted wallet custody. Such architectures separate an agent’s ability to propose or execute actions from ultimate control over funds, illustrating why regulators may need to evaluate permission boundaries rather than simply whether AI participated in a transaction.
Payments networks are developing similar controls. Visa’s Intelligent Commerce infrastructure uses tokenized credentials, spending limits and authorization policies to allow agents to initiate purchases without receiving unrestricted access to payment credentials. The emerging design pattern is delegated authority rather than unlimited autonomy, with identity, revocation and transaction limits remaining attached to the human or business granting permission.
Correlated Trading Creates a Separate Market Risk
Selig also identified risks that extend beyond individual authorization. Agents may respond unexpectedly to market conditions, while systems based on similar models could produce correlated trading behavior. At machine execution speeds, synchronized responses across many agents could create new challenges for surveillance and risk management, even when each individual system is operating within its assigned permissions.
Those concerns echo the broader development of agentic financial infrastructure. Crossmint’s Agentic Cards API similarly places spending policies and auditable controls between AI agents and payment credentials. Identity and authority are increasingly being designed into the infrastructure itself because conventional authentication does not necessarily reveal whether software is following a user’s current intent.
Traditional banks are confronting the same problem from the opposite direction. Several major U.S. institutions have begun restricting third-party AI agents that access accounts using customer credentials, while controlled read-only access remains more acceptable in some cases. A valid customer login can authenticate an account without proving that every subsequent action taken by an agent was specifically intended by the customer, creating the attribution problem Selig highlighted.
The CFTC has not proposed a KYA rule or defined a registration regime for agent developers. The immediate regulatory development is that autonomous financial software has moved onto the agency’s formal policy agenda, with the Frontier Forum examining how existing rules apply when software rather than a person increasingly performs market-facing functions.